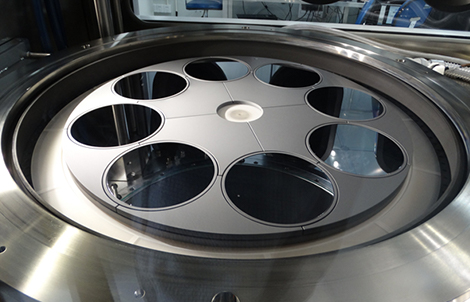
Silicon wafers are located at the upstream of the semiconductor industry chain and are the main raw materials for semiconductor devices and solar cells. They are mainly used in the photovoltaic and semiconductor fields. Downstream demand has continued to grow in recent years.In terms of different fields, the production capacity of photovoltaic silicon wafers is mostly concentrated in my country. Leading companies such as Zhonghuan and Longi are strong and have world-leading production technology. Compared with photovoltaic silicon wafers, semiconductor silicon wafers have more complex manufacturing processes, more application scenarios, and higher market value. However, my country's semiconductor silicon wafer industry started late and its development level is relatively backward. The global market is monopolized by Japanese manufacturers. The mainstream 12-inch silicon wafers in the market have not yet achieved large-scale production in my country and are heavily dependent on imports. Domestic companies represented by Shanghai Silicon Industry are working hard to break through technological barriers, and there is broad room for domestic substitution.(1) Silicon wafers have a wide range of downstream applications and are important materials for semiconductor devices and photovoltaic cells.Silicon is a good semiconductor material with good high temperature and radiation resistance, making it particularly suitable for the production of high-power devices. Silicon is used as raw material, and single crystals are pulled into silicon rods, which are then cut into silicon wafers. Silicon wafers are mainly used in the semiconductor and photovoltaic fields. Semiconductor silicon wafers have higher requirements in terms of crystal quality, shape, size, and purity than photovoltaic silicon wafers. The purity of photovoltaic silicon wafers is required to be between 4N and 6N.Semiconductor silicon wafers have a purity of approximately 9N-11N (99.9999999%-99.99999999%), with a more complex manufacturing process and a wider range of downstream applications. Semiconductor silicon wafers are at the very top of the supply chain, primarily used in integrated circuits, discrete devices, and sensors. They are a key material for chip manufacturing, influencing the development of downstream industries like automotive and computing, and are the cornerstone of the semiconductor industry chain.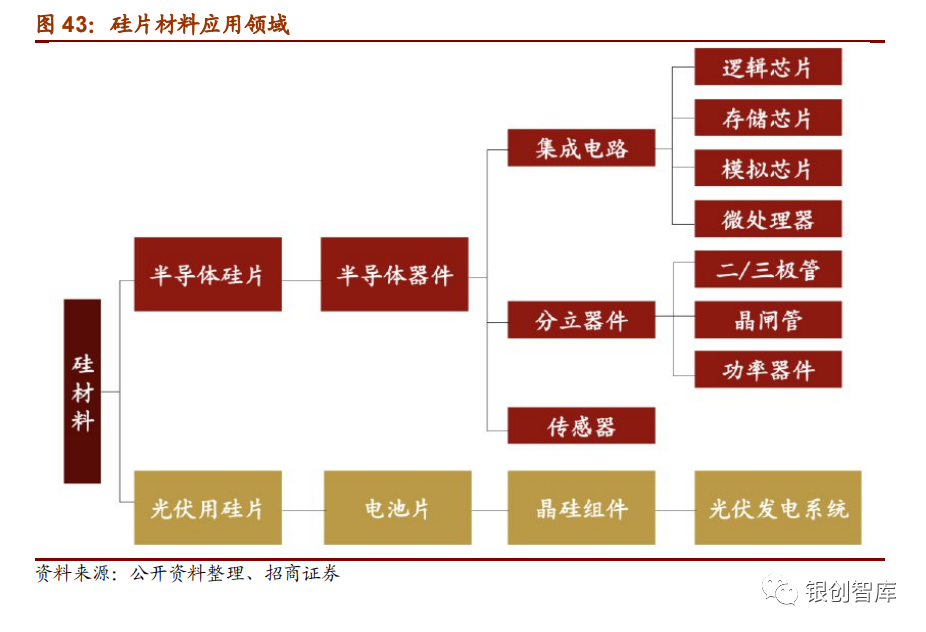 (2) Photovoltaic silicon wafers: China has the largest production capacity and leading enterprises are strong.The photovoltaic industry is one of the country's strategic emerging industries. Photovoltaic silicon wafers are located at the upstream of the photovoltaic industry chain. In recent years, their demand has been increasing.According to CPIA forecasts, the annual installed capacity of the global photovoltaic market will reach 150GW in 2021, which has broad market and development prospects. my country is the world's largest producer of photovoltaic monocrystalline silicon wafers.According to statistics from the Silicon Branch of the China Nonferrous Metals Industry Association, as of the end of 2019, my country's monocrystalline silicon wafer production capacity reached 115GW, accounting for 97.6% of the global total. Leading companies Longi and Zhonghuan hold over 50% of the domestic monocrystalline silicon wafer market share and are continuing to expand their production capacity. New players such as Shangji CNC and Beijing Yuntong are also accelerating their expansion efforts.According to statistics from various company reports, my country's monocrystalline silicon wafer production capacity was approximately 190GW in 2020, and it is expected that by the end of 2021, the domestic monocrystalline silicon wafer production capacity will reach 240GW.(3) Semiconductor silicon wafers: heavily dependent on imports, with ample room for domestic substitutionBenefiting from the technological advancement of semiconductor products and the increase in the categories of downstream related electronic consumer products, the demand for semiconductor silicon wafers has increased year by year and the scale has continued to grow. In 2020, the global shipment of semiconductor silicon wafers reached 1.241 billion square inches.According to Gartner's forecast, the global silicon wafer market will reach approximately US$11 billion in 2020, and the market prospects for semiconductor silicon wafers are broad.Due to high technical barriers in the semiconductor silicon wafer industry, the global semiconductor silicon wafer industry is currently dominated by giants, resulting in a high degree of concentration and a small presence of manufacturers in mainland China. In 2020, the top five global silicon wafer suppliers—Japan's Shin-Etsu Chemical, Japan's SUMCO, Taiwan's GlobalWafers, Germany's Silitronic, and South Korea's SK Siltron—held a combined market share exceeding 80%. Mainland my country's Shanghai Silicon Industry Co., Ltd. held a relatively small market share of approximately 2.2%.The larger the silicon wafer, the higher the unit wafer production efficiency. Since the 1970s, silicon wafers have been moving towards larger sizes. Today, the world's largest mass-produced silicon wafer is 300mm, or 12-inch. Demand for 12-inch wafers has been rising in recent years. According to a forecast by Japan's Sumco, the compound annual growth rate (CAGR) for 12-inch wafers from 2020 to 2024 could reach 5.1%. Global semiconductor silicon wafer production capacity is primarily concentrated among industry giants. my country's semiconductor silicon wafer industry started late and has lagged behind, with only a few companies capable of producing 200mm (8-inch) silicon wafers. Before 2017, my country's 12-inch silicon wafers were entirely imported.The production of large silicon wafers requires very high silicon purity, as well as exceptionally high processing requirements for chamfering and precision grinding. my country's technological capabilities lag behind, and large-scale production of 12-inch silicon wafers has yet to be achieved. Shanghai Silicon Industry achieved large-scale sales of 12-inch silicon wafers in 2018, breaking the deadlock in domestic production of large-size silicon wafers. 12-inch silicon wafers remain the mainstream in the current silicon wafer market, giving domestic manufacturers an opportunity to catch up. There is still considerable room for domestic substitution in large-size silicon wafers.In order to promote the localization of semiconductor silicon wafers, an important material, the Chinese government has also introduced a series of policies to support industrial development, promote the research and development and manufacturing of large-size silicon wafers, and promote the development of the semiconductor industry.(4) Important listed companiesDomestic silicon wafer manufacturers cover a wide range of businesses, often involved in both photovoltaic and semiconductor wafer production. Zhonghuan Semiconductor and Longi Green Energy Technology Co., Ltd., leading photovoltaic silicon wafer manufacturers, are strong and maintain their leading position. Domestic manufacturers of semiconductor silicon wafers are catching up rapidly, with Shanghai Silicon Industry leading the way in the 12-inch silicon wafer market. In addition, companies such as Zhonghuan Semiconductor, Lianwei Microelectronics, and Super Silicon Semiconductor have also entered the large silicon wafer market. China is the world's largest semiconductor end market. With the continued expansion of China's chip production capacity, the market size of my country's semiconductor silicon wafers is expected to grow rapidly, and the large silicon wafer market has broad development prospects.
Silicon carbide, a third-generation semiconductor material with exceptional performance, is a key raw material for power devices. In recent years, countries around the world have invested heavily in developing related industries. However, the entry barriers to entry in the silicon carbide industry are relatively high, and my country's production technology is relatively backward. The industry landscape is currently dominated by the United States, with Cree alone accounting for 62% of the global market share for conductive silicon carbide wafers. The silicon carbide market holds promising prospects. In recent years, it has steadily penetrated areas such as electric vehicles, photovoltaics, rail transit, and smart grids, generating strong downstream demand and a continuously expanding market. my country is also developing a comprehensive silicon carbide industry chain. The number of related patents has been increasing this year, and the market share of wafer manufacturers such as Tianke Heda has also been increasing year by year. This suggests significant potential for future growth in my country's silicon carbide industry.(1) Third-generation semiconductor materials, the cornerstone of new energy and 5GSilicon carbide is the most mature wide bandgap semiconductor material currently developed and is also a representative material of the third generation of semiconductor materials.Silicon carbide (SiC) offers numerous advantages: stable chemical properties, high thermal conductivity, low thermal expansion coefficient, and resistance to wear and high pressure. Products using SiC can be 50% smaller and have 80% lower energy loss than products with the same electrical parameters. These properties have attracted significant attention worldwide, with countries devoting significant effort to promoting the development of related industries. Major international semiconductor giants have also invested heavily in the development of SiC devices. As the technology matures and manufacturing costs decrease, SiC is being applied to various power devices. In recent years, the penetration of SiC power devices in new energy vehicles has continued to rise, making them a crucial raw material for SiC and GaN devices in future new energy and 5G communications applications.
(2) Europe and the United States occupy a key position in the SiC industry chainThe silicon carbide production process is divided into three steps: single crystal growth, epitaxial layer growth and device manufacturing, which correspond to the three links of the industrial chain: substrate, epitaxy, devices and modules. The silicon carbide industry has a high technical threshold and a long R&D time.For many years, countries and regions such as the United States, Europe, and Japan have continuously improved the preparation technology of silicon carbide single crystals, developed and manufactured related equipment, and have great advantages in all links of the silicon carbide industry chain.Industry giant CREE is strong. Its subsidiary Wolfspeed has vertically integrated production capabilities and leads the power and RF device markets. European companies such as Infineon and STMicroelectronics have a complete SiC production and application industry chain. Japanese companies such as Rohm Semiconductor and Mitsubishi Electric are leaders in the development of SiC power modules. In recent years, the number of foundry companies has also increased, with companies from mainland China and Taiwan gradually entering the market. Foundry companies include Sanan Integrated Circuit (China) and EpiSilicon Technology (Taiwan).Currently, the silicon carbide industry is dominated by the United States. For example, in 2018, the United States accounted for over 70% of global production of conductive silicon carbide wafers, a key product. Cree alone held a 62% market share, with the remainder largely held by other Japanese and European companies. Chinese companies held a mere 1.7%.(3) The development of new energy vehicles and photovoltaic industries promotes the growth of the silicon carbide marketSilicon carbide is an ideal material for extreme power devices, resistant to high temperatures and high pressures, with high energy conversion efficiency and a wide range of applications. Currently, there are four main application scenarios for silicon carbide power devices:1) New energy vehicles: main inverters in motor drive systems; 2) Photovoltaics: photovoltaic inverters; 3) Rail transit: power semiconductor devices; 4) Smart grid: solid-state transformers, flexible AC transmission, flexible DC transmission, high-voltage DC transmission and distribution systems.With the further development of silicon carbide power devices, their penetration rate continues to increase across various fields. According to Yole, the global market for automotive SiC power devices is expected to reach US$1.93 billion by 2024, corresponding to a compound annual growth rate of 29% from 2018 to 2024. According to Tianke Heda's prospectus, the proportion of silicon carbide power devices in photovoltaic inverters will reach 50% by 2025, and the proportion of silicon carbide devices in rail transit applications will also gradually increase.Driven by demand for electric vehicles and photovoltaic inverters, the emerging market for silicon carbide and gallium nitride power semiconductors is expected to exceed US$1 billion in 2021, according to Omdia's forecast. According to IHS Markit data, the market size of silicon carbide power devices was approximately US$390 million in 2018. Benefiting from the growing demand for new energy vehicles and the development of the photovoltaic industry, the market size of silicon carbide power devices is expected to exceed US$10 billion by 2027. The silicon carbide industry has sufficient growth momentum.(4) There is a strong demand for domestic production of silicon carbide, and the industrial system is gradually being laid out.my country is the largest market for silicon carbide (SiC), but its industry is currently far from complete. Domestic research and development (R&D) and manufacturing of SiC materials and power devices are primarily conducted by research institutes and universities, lacking the capacity for large-scale production. While China currently holds a low market share in the SiC sector, it is gradually developing various links in the industry chain and is expected to achieve strong growth. The government also prioritizes the development of this industry, promoting its growth through the 863 Program and the National 02 Major Project. Silicon carbide substrates have also been included in the 13th Five-Year Plan's "Catalogue of Key Products for Strategic Emerging Industries." Patent filings show 2,887 SiC-related patents filed in my country between 2018 and 2020. This increase in patents demonstrates the continued improvement of SiC technology reserves among Chinese companies. In the past two years, a small number of Chinese companies have entered the SiC field. Chinese companies primarily focus on 4-inch SiC single crystal substrates, but have now developed 6-inch substrates. SiC wafer manufacturers, primarily Tianke Heda and Shandong Tianyue, have experienced rapid growth and significantly increased their market share. Sanan Optoelectronics is also making in-depth layouts in the silicon carbide industry chain.3. High-purity metal sputtering targetsSputtering targets are one of the core materials for integrated circuits and have been developing towards high sputtering rates and high-purity metals in recent years.Its downstream application scenarios mainly include semiconductors, panels, and solar cells. With the development and improvement of the consumer electronics terminal market, the downstream demand for high-purity metal sputtering targets continues to rise. The compound growth rate of the global target market from 2013 to 2020 reached 14%, and the market size has gradually expanded. The industry barriers of sputtering targets are high. American and Japanese companies have mastered the core technology and monopolized the global market. my country's sputtering target industry started late and is relatively backward, but the market demand is leading the world, and there is a large space for domestic substitution. Domestic companies are gradually breaking through technical bottlenecks to break the monopoly of the United States and Japan in the high-end target market.Work hard to take advantage of the situation.(1) Core materials of integrated circuitsSputtering is a key technology for preparing thin-film materials. It involves using ions generated by an ion source to accelerate and converge in a vacuum, forming a high-energy ion beam. This beam then bombards a solid surface. The ions exchange kinetic energy with the atoms on the solid surface, causing the atoms on the solid surface to detach and deposit on the substrate. The bombarded solid serves as the raw material for thin-film deposition, known as the sputtering target. Sputtering is used to deposit dielectric layers, conductor layers, and even protective layers within integrated circuit components.Ultra-high-purity metals and sputtering targets are essential components of electronic materials. The sputtering target industry chain primarily encompasses metal purification, target manufacturing, sputtering coating, and end-use applications. Target manufacturing and sputtering coating are key links in the entire sputtering target industry chain, requiring high process capabilities and presenting significant barriers to entry. Targets are currently evolving towards high sputtering rates, controlled grain orientation, large sizes, and high-purity metals.The main high-purity metal sputtering targets now include aluminum targets, titanium targets, tantalum targets, tungsten-titanium targets, etc., which are the core materials for the preparation of integrated circuits.(2) Consumer electronics drives the expansion of the target material marketThe downstream market capacity for high-purity sputtering target products has been gradually expanding in recent years: 1) Semiconductor Industry: With the continued growth in demand for semiconductors in consumer end-use areas such as smartphones and tablets, the semiconductor market capacity has further increased. The semiconductor industry requires a wide variety of sputtering targets and the demand is high. The stable growth of the downstream market will strongly promote the growth of sputtering target sales. 2) Flat Panel Display Industry: In recent years, liquid crystal displays have gradually become the mainstream display technology in the world and have been widely used in the flat panel display market. To ensure the uniformity of large-area film layers in flat panel displays, sputtering technology is increasingly used to prepare these layers.Since the 1990s, the rapid development of terminal application markets such as consumer electronics has promoted the development of the high-purity sputtering target industry, and the market size has grown rapidly.From 2013 to 2020, the global sputtering target market size is expected to increase from US$7.56 billion to US$19.563 billion, with a compound growth rate of 14.42%.(3) High-end target material research and production are mainly concentrated in the United States and JapanWell-known foreign target companies have accumulated decades of experience in target research and development and production. Globally, the number of companies involved in each link of the sputtering target industry chain is basically distributed in a pyramid shape. The technical threshold for high-purity sputtering target manufacturing is high, and the equipment investment is large. The number of companies with large-scale production capabilities is relatively small, and they are mainly distributed in the United States, Japan and other countries and regions. At present, there are four major companies in the global sputtering target market, namely JX Nippon Mining and Metals, Honeywell, Tosoh and Praxair, with market shares of 30%, 20%, 20% and 10% respectively, and a total monopoly of 80% of the global market share. Among them, the highest-end wafer manufacturing target market is basically monopolized by these four companies, which together account for about 90% of the global wafer manufacturing target market share. JX Nippon Mining and Metals is the largest, accounting for % of the global wafer manufacturing target market share.The case is 30%.
(4) Domestic demand for high-end targets is strong, and there is a large space for domestic substitutionIt is estimated that in 2019, domestic demand accounted for over 30% of the global target material market, while domestic manufacturers supplied approximately 30% of the domestic market. High-end targets are primarily imported from the United States, Japan, and South Korea, leaving the domestic target material market with at least tenfold import substitution potential. Regarding targets for semiconductor users alone, statistics from the China Electronic Materials Industry Association indicate that the domestic semiconductor sputtering target market was worth RMB 1.615 billion in 2020. By 2025, the domestic sputtering target market for wafer manufacturing is projected to grow to US$217 million, and that for packaging to US$118 million, for a total of US$335 million, or approximately RMB 2.345 billion.Due to its development history and technological limitations, my country's high-purity sputtering target industry started late and is still a relatively new industry. The main high-purity sputtering target manufacturers are all invested by state-owned capital and a small amount of private capital. Compared with the sputtering targets produced by internationally renowned companies, my country's sputtering target production level still lags far behind, and its market influence is very limited. The country has promoted the development of the industry through various policies, such as the "New Materials Industry Development Guide" issued in 2016.It is proposed to strengthen the research and development of high-purity metal sputtering target production technology. The tax-free period for imported targets expired at the end of 2018, opening up the possibility of domestic substitution of targets. Currently, China is gradually breaking through key technological barriers, breaking the backward situation where core sputtering target technology was monopolized by the United States and Japan and the products had to be imported entirely. Currently, some products of Chinese target manufacturers have reached internationally advanced levels, and their product quality has been recognized by downstream companies both domestically and internationally. By building factories near downstream companies, target prices could be 10%-15% lower than those of foreign manufacturers. The necessity and strategic significance of substitution are clear.(5) Related listed companiesAmong domestic companies, Ashi Chuang, Longhua Technology, Youyan New Materials, and Jiangfeng Electronics have significant production capacity for target materials. Ashi Chuang and Longhua Technology primarily produce products for panels. Jiangfeng Electronics' products cover the semiconductor, solar photovoltaic, and panel sectors, while Youyan New Materials primarily produces semiconductor targets.
source:Yinchuang Think Tank